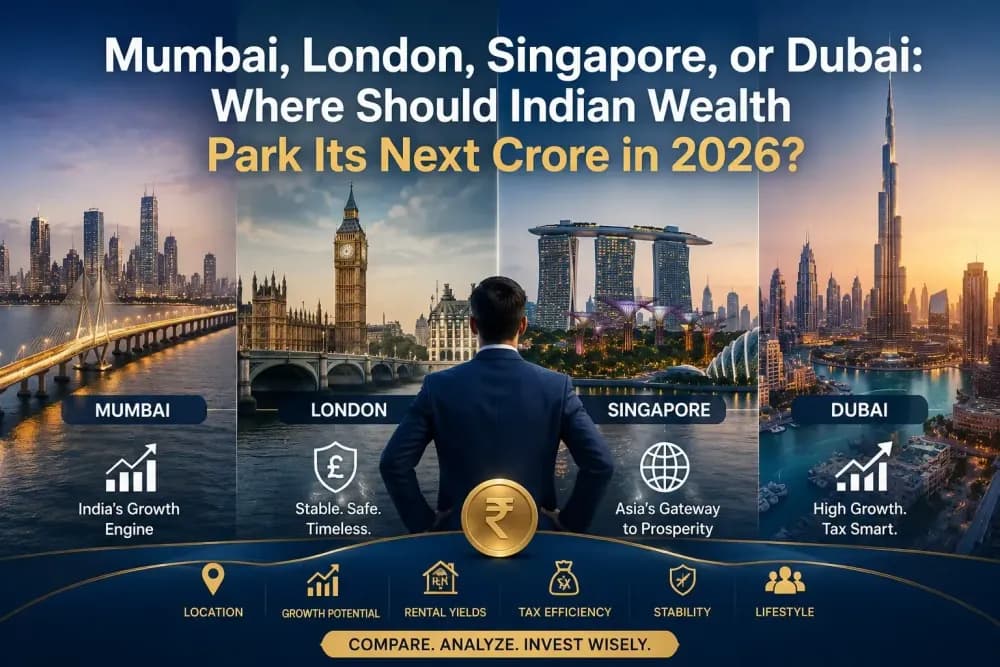
Mumbai, London, Singapore, or Dubai: Where Should Indian Wealth Park Its Next Crore in 2026?

Table of Contents
Indian wealth has never been more mobile. LRS remittances are climbing. Family offices in Gujarat, Maharashtra, and Karnataka are actively building international portfolios. And the conversation in every private wealth boardroom keeps circling back to the same question: if I have a crore to deploy in real estate outside India, where does it work hardest? The honest answer involves comparing four cities - each with advantages, each with trade-offs. Let me walk you through the arithmetic the way I would if you were sitting across from me in my Dubai office.
Mumbai: The Familiar Bet That No Longer Adds Up on Yield
Mumbai needs no pitch to Indian investors. But the numbers have become difficult to defend. Rental yields across premium South Mumbai locations average 2–2.5%. A two-bedroom apartment in Worli costing ₹4–5 crore fetches ₹80,000–100,000 per month in rent. After maintenance charges, society fees, and income tax on rental income, the real return dips below 2%.
Stamp duty in Maharashtra sits at 6%. GST applies to under-construction purchases. Capital appreciation over the past five years has been single-digit annually in most micro-markets. For UHNIs who already own multiple Mumbai properties, the marginal return on adding one more is diminishing.
London: The Prestige Play With Eroding Economics
London has been the default international allocation for wealthy Indian families for decades. But the post-Brexit reality has changed the calculus. Stamp duty surcharges for overseas buyers now reach 17%. Non-dom tax rules have been overhauled. Rental yields average 3–4%. And the pound-rupee exchange rate adds a layer of currency volatility that eats into returns.
A one-bedroom apartment in central London starts around GBP 500,000 - roughly ₹5.5 crore - and delivers GBP 18,000–22,000 in annual rent. After tax and management fees, you are looking at 2.5–3% net yield in a depreciating currency. The prestige is real. The financial case is becoming harder to make.
Tax-Friendly Real Estate Markets: Why Dubai Is Winning Over Singapore
Singapore is well-regulated, transparent, and exceptionally liveable - all qualities Indian investors respect. But the additional buyer stamp duty for foreign purchasers now stands at 60%. That is not a typo. A SGD 2 million property costs an Indian buyer an additional SGD 1.2 million just in stamp duty.
Rental yields average 3–4%, which is respectable. But the after-tax, after-duty return on invested capital makes Singapore viable only as a residence, not as a pure investment destination.
Dubai: Where the Arithmetic Keeps Outperforming Every Comparison
Dubai delivers gross rental yields of 6–9% depending on the community. There is zero income tax on rental earnings. Zero capital gains tax on property sales. The Golden Visa provides ten-year residency for investments above AED 2 million. Freehold ownership is available to all nationalities in designated zones. The AED is pegged to the US dollar, eliminating the currency uncertainty that plagues NRI investments in the UK and Europe.
Luxury apartments for sale in Dubai - in communities like Dubai Hills Estate, Dubai Marina, and Business Bay - cost 50–70% less per square foot than comparable addresses in London or Singapore. A one-bedroom apartment in Dubai Marina, with views of the most photographed skyline in the world, costs less than an equivalent unit in central Mumbai while delivering three to four times the rental return.
Off-plan apartments in Dubai come with developer payment plans - 80/20, 60/40, post-handover instalments stretching three to five years - that no other global city offers. For Indian investors managing cash flows across businesses, that structural flexibility transforms how you build an international property portfolio.
What the Smart Money Is Actually Doing
The sophisticated Indian family offices I work with are not choosing one city and going all in. They are allocating a dedicated international real estate sleeve - typically 15–25% of total portfolio - with Dubai as the core holding. Some hold a London flat for personal use and a Dubai Hills villa for yield and appreciation. Others have exited Singapore entirely and redirected that capital into Dubai's emerging corridors.
Indians have consistently ranked among the top three nationality groups by transaction volume in Dubai for the past several years. That is not a sentiment-driven trend. It is a structural reallocation of how Indian wealth thinks about global real estate.
For a personalised global allocation comparison and Dubai-specific investment roadmap, reach out to Seema Balwani at Xperience Realty - seema.b@xrealty.ae
Thinking about your next Dubai property?
Talk to an XRealty specialist — market guidance, shortlists, and honest advice, no obligation.
Related Articles
 Invest In Dubai
Where to Buy in Dubai in 2026: Five Areas for Different Buyer Priorities
A practical guide to five Dubai locations for end users, long term growth buyers and income focused investors.
 Market News
One Visa, Six Gulf Countries: What the GCC Grand Tours Visa Could Mean for Dubai Property
Explore how the planned GCC Grand Tours Visa could influence Dubai tourism, holiday homes and property demand—and what remains unconfirmed.
 Off Plan
Dubai Islands Explained: Five Islands, Five Different Property Decisions
Understand Dubai Islands through its five planned districts, from Central and Shore Island to Golf, Marina and Elite Island, before choosing a property.